
Jensen Huang—the man who spent 33 years building Nvidia (NVDA) into the powerhouse behind the AI boom—resigned Thursday amid allegations involving a woman suspected of spying for China.
Investors panicked on the news.
Nvidia shares opened Thursday around $150, down from roughly $220 just a few weeks earlier. The stock recovered some of those losses by the close, finishing near $166.
It’s understandable why investors are nervous. Huang was the face of Nvidia. He helped turn the company from a graphics chipmaker into one of the world’s most valuable businesses.
But when you look past the headlines, the case for Nvidia is bigger than Huang.
And with the stock down sharply from its recent highs, that distinction could be worth billions to investors.
Nvidia no longer depends on Jensen
There’s no question that Huang was integral to Nvidia’s success. He recognized the potential of artificial intelligence years before most of Wall Street and positioned Nvidia to dominate the industry.
But the business he built is now supported by thousands of engineers, an enormous software ecosystem, and customers spending billions to build AI infrastructure. Those advantages don’t disappear overnight just because Huang is no longer at the helm.
Take Nvidia’s latest financial results. In August, the company reported quarterly revenue of $96.2 billion, up 106% from a year earlier. And its Data Center business, which supplies the chips powering AI systems, grew even faster: 117% to $89 billion.
Nvidia also expects revenue to reach about $108 billion in its next quarterly report.
That demand is being driven by some of the world’s largest technology companies, which are pouring money into AI infrastructure.
Another encouraging sign comes from Taiwan Semiconductor (TSM), the company that manufactures Nvidia’s chips.
TSMC reported record October revenue, up 14.7% from September and nearly 60% from a year earlier. Of course, TSMC supplies chips to many companies beyond Nvidia. But those numbers reinforce the broader point: Demand for advanced semiconductors remains strong.
And Nvidia has another advantage that will be difficult for competitors to overcome.
Nvidia’s biggest competitive advantage
When most people think about Nvidia, they think about its powerful AI chips.
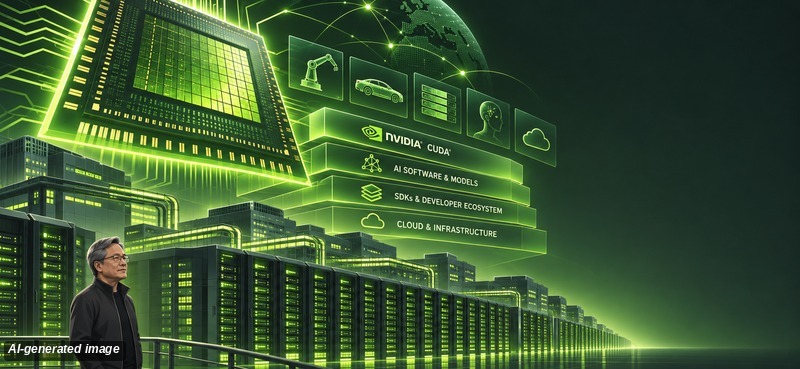
But one of the company’s greatest advantages is CUDA, Nvidia’s software platform that allows developers to build applications using its graphics processors.
Over the years, countless companies and developers have built their AI systems around this technology. Moving to a competing platform can mean rewriting code, retraining employees, and potentially disrupting existing systems. And that creates enormous costs.
That’s a major reason Nvidia has been able to maintain its leadership despite growing competition from AMD, Broadcom, and other chipmakers.
While Huang helped create that advantage… it now exists independently of him.
Meanwhile, Nvidia’s next-generation Vera Rubin platform is already in production, giving the company another opportunity to capitalize on growing AI demand.
The selloff has changed Nvidia’s valuation
Just a few weeks ago, Nvidia was trading around $220 per share. After the recent selloff, the stock closed Thursday at roughly $166.
That dramatic decline has made Nvidia considerably cheaper relative to its expected earnings.
The company now trades at approximately 14x forward earnings, compared with roughly 18x for the broader S&P 500.
In other words, investors are now paying a lower multiple than the broader market for a business whose revenue more than doubled last quarter.
Of course, its future earnings estimates still need to materialize.
On Tuesday, November 17, investors will get their first major financial update since Huang’s departure. The numbers—and management’s outlook—should help determine whether the recent selloff reflects a genuine deterioration in Nvidia’s business or primarily the uncertainty surrounding its leadership.
The risks
We don’t want to minimize the significance of losing Huang. He was one of the industry’s most influential dealmakers, with relationships spanning Silicon Valley, Washington, and some of Nvidia’s largest customers. Replacing that kind of leadership won’t be easy.
For now, longtime CFO Colette Kress has stepped in as interim CEO while the company searches for a permanent replacement. Kress has been with Nvidia since 2013 and understands its finances and operations. That’s reassuring, but running the entire company presents a different challenge.
There’s also the ongoing controversy surrounding Huang. While his resignation may reduce some of the uncertainty about Nvidia’s leadership, the company could face additional scrutiny over its dealings in China.
The direct revenue exposure from certain older chip shipments to China is relatively small. Nvidia reported that Hopper shipments to China accounted for less than 1% of Data Center revenue last quarter. But broader regulatory or political consequences could still follow.
These are legitimate risks that could continue weighing on the stock. Still, we believe Nvidia’s underlying business is strong enough to withstand this leadership transition.
The bottom line
Jensen Huang’s departure creates real uncertainty about the company’s future. But Nvidia has spent decades building advantages that extend far beyond its founder… from its technology and engineering talent to the software ecosystem that keeps customers coming back.
Meanwhile, AI infrastructure spending continues to drive extraordinary growth.
With Nvidia shares trading at a much lower valuation than just a few weeks ago, we’re still bullish on the company’s long-term prospects.
The next test comes Tuesday, when Nvidia reports earnings.
If the company can show its growth and strategy remain on track, investors should move on from the CEO drama and return their attention to the business fundamentals.
Want to know how we’re managing our Nvidia (NVDA) position?
Yesterday, Frank shared an update revealing exactly how we’re approaching the stock in our Curzio Alpha portfolio.
Get the update as soon as you join.
Curzio Research publishes market commentary for informational and educational purposes. The opinions expressed and market conditions when the content is published may change. It is not personalized investment advice or an offer to buy or sell securities. Investing involves risk, including possible loss of principal. Do your own research and consult a qualified investment professional before making investment decisions.